

As I sat there listening to a friend who owns a small business, I wondered whether there are different tax regimes in Kenya depending on what form of commercial activity one undertakes.
Despite working in tax advocacy for the past nine years, this was the first time I was coming across a VAT Withholding Tax (henceforth referred to as VWT).
Indeed, this is something different from what is generally understood as Value-Added Tax (VAT) and the fact that many small businesses are finding themselves being ambushed by it goes to show how much Kenyan taxation requires a lot more democracy.
VAT is the standard rate of 16 per cent tax that is charged on the consumption of goods and services supplied or purchased. Businesses charge it as part of the cost, then remit the difference between the price and the tariff to the government. Every good or service, from fuel to bread, usually has a 16 per cent cost added to it.
The VWT, on the other hand, is a mechanism to collect VAT at the point of supplies provision. This means that for selected businesses, there is a tax within a tax for every purchase they make. In this case, the Kenya Revenue Authority (KRA) appoints selected businesses or individual entities as their agents to deduct this tax at a fixed rate of 2 per cent on the advance payment to their suppliers.
Essentially, once the supplier gives you the price of a good or service inclusive of 16 per cent VAT, if you are appointed a KRA agent to implement VWT, you would hold on to 2 per cent of that payment for remittance to the tax collector.
This must then be reconciled through the electronic Tax Invoice Management System (eTIMS). The system has unfortunately been experiencing frequent partial or full downtimes in recent months, preventing transaction matching between sellers and buyers for accurate KRA determination of tax demands or claims.
My friend had no idea how his business had been selected to become a KRA implementing agent. Moreover, even when he could not reconcile the taxes using eTIMS due to frequent system downtimes, his business was still automatically liable for penalties due to noncompliance.
This happened because even as the eTIMS system was partially shut down, other functioning segments of the tax software platform continued accumulating taxes from other regular purchases he transacted, and recorded them onto the eTIMS portal as he carried out other business.
This revelation by my friend was to me mind-boggling because I could immediately see the tense and awkward haggling that could harm a business relationship given the current difficult commercial environment.
Such are the tribulations small businesses are facing on top of tax contestations around cash flow mismatches, informal supply chain problems, eTIMS-related costs due to system glitches, invoicing evidence rules, and digital literacy demands for revenue compliance.
Looking at Section 42 of the Tax Procedures Act of 2015, it emerges that the application of the law in this instance is vague, thereby conferring unfettered discretionary powers on public officials under the authority of the KRA Commissioner General.
There are no objective criteria as to how VWT agents are determined and these appointments then come across as arbitrary decisions that not only confuse taxpayers but also leave them paralytically unable to predict the legal consequences of their actions.
It came as no surprise a few weeks later that traders had become angry over another tax that consolidated cargo clearance charges. Though separate from the VWT issue, the manner of application of this tax is annoyingly similar.
This has resulted in protests by traders that have forced President William Ruto to order a review of customs costs and differentiated implementation in the handling of ordinary consignments compared to high-value cargo.
This means that containers carrying commercial merchandise, everyday consumer items, bulk or general cargo of low value will continue to pay KSh 2 million for clearance.
Meanwhile, shipments of luxury goods, specialized electronics, high-end motor vehicles, and industrial machinery will undergo further assessment based on the value of the goods in the container, which is likely to raise costs.
The two examples above are a stark reminder of Professor Migai Akech’s treatise on the undemocratic application of administrative law in taxation, where power is abused and not practised based on the principles of equity, fair treatment, and accountability.
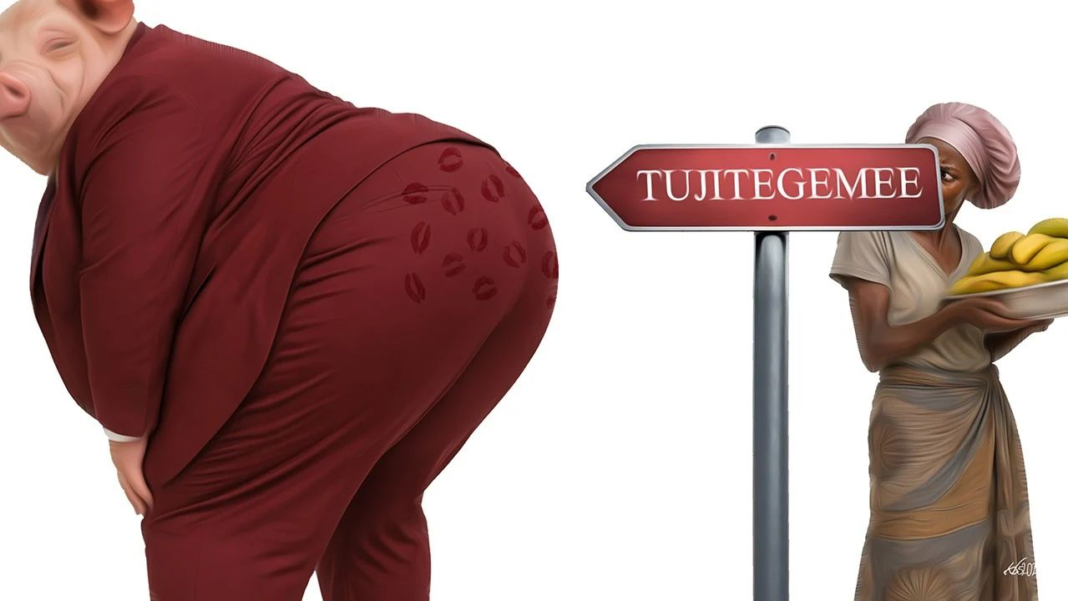
Politically, this transforms taxation into an oppressive tool that can break into anyone’s piggy bank at any time to attain undisclosed national budgetary goals or silence dissenting voices at the whim of the powers that be, a “preserve of autocratic governance” in which Kenya is governed as a tyrannical barony.
As a result, tax collection becomes inefficient because citizens are dissuaded from active compliance due to their distrust of established policies or processes.
Despite their willingness to pay taxes – as captured in research by Twaweza East Africa on Taxing Matters – and their being aware of the publicized intent for revenue collection measures to help settle debt obligations and service delivery demands, Kenyans are sceptical of tax authorities because they do not deem them to be fair.
Kenya’s National Taxpayers Association (NTA) points out in its 2025 Tax Perception Survey Report that informal sector inclusion is highly contested, resulting in lingering pessimism because KRA is viewed as obstructive while its officers are perceived as dismissive and unhelpful in explaining tax law and the accompanying regulatory demands.
This is compounded by underlying grievances such as awareness of tax avoidance and fraudulent financial practices like corruption or theft that are not properly punished within the context of poor economic growth as captured by the East African Tax and Governance Network (EATGN) in the 2021 Kenya National Tax Outlook Survey.
With this in mind, how then can it be that anyone can simply be ambushed to become a KRA agent without a clearly stated legal mechanism categorizing taxpayers and clearly ascertaining their legal obligations for such roles?
First, this flies in the face of the right to fair administrative action under Article 47 of the Constitution, thereby making it an unrelatable process that comes off as a whimsical application of the law.
This is because it haphazardly changes the taxpayer’s legal obligations by designating roles which simultaneously expose one to compliance costs, penalties, interest, and unforeseen duties without clear justification, prior notice, consultation, or explanation of the criteria applied in the appointment of a VWT agent.
Secondly, it is an unscrupulous transfer of costs and other administrative burdens to private entities, thereby infringing on the right to property under Article 40 of the Constitution, where incomes are broadly protected as “property of any description”.
In this instance, appointed agents deploy time (explaining processes at length to their fellow taxpayers who would obviously feel shortchanged discussing tax complexity while bargaining over margins with a non-state entity), resources, personnel, and finance systems without compensation based on unclear statutes.
Thirdly, Section 23A of the Tax Procedures Act disproportionately targets small businesses while Section 23A (3a) specifically shifts responsibility from suppliers to purchasers.
The VWT, therefore, adversely affects commercial activities at a small or micro level; in remote areas with poor internet access; for those trading informally or operating with limited digital literacy – for example, the elderly; and for those that cannot afford hardware or software upgrades.
A straight line can therefore be drawn between the negative public sentiment against eTIMS and the problem of how the current application of tax systems is not only inconvenient and prohibitive but is also punishingly expensive for small businesses or traders.
This is because it is inconsistent with the constitutional right to equality and freedom from discrimination under Article 27(1) of the constitution that guarantees that eTIMS application should offer equal protection and benefits under the law. Furthermore, Article 27(4) prohibits direct or indirect discrimination.
One must ask: how does a purchaser generate tax invoices within an unclear statutory framework where they cannot verify that the supplier’s annual turnover is below the legally prescribed threshold? Doesn’t that expose them to tax liabilities based on information they have no access to and that is the exclusive knowledge of the supplier?
Consequently, small-scale farmers and small trading operations are finding themselves subject to administrative actions that amount to unjustified interference that manifests as punitive assessments that charge them with noncompliance.
Going by paragraph 5(2) of the Tax Procedures (Electronic Tax Invoice) Regulations of 2024, taxpayers face further challenges because the existing process for notifying the KRA whenever the system is not working is impracticable and shifts the burden or consequences of a failed digital platform onto taxpayers.
In effect, a taxpayer is expected to “a) notify the Commissioner in writing within twenty-four hours of the user’s inability to use the system; and b) record sales using any other means as may be specified by the Commissioner” if they’re having problems using the system.
Additionally, the appeals timelines become unreasonable when businesses cannot use the relevant system functions because of connectivity problems, technology capabilities, or disruptions caused by lack of access to system components that are experiencing outages, while other capacities are accessible, functional, and working.
As highlighted by Professor Akech, in the eyes of the public, most KRA failures can be attributed to the misapplication of discretionary powers or their outright abuse. This is made worse by the fact that the KRA does not seem to be obligated to respond within a reasonable timeframe to the satisfaction of taxpayers.
Hence, KRA acts in a high-handed manner that renders its processes excessively demanding and costly. This is even more painfully so when one is faced with long and winding judicial interventions when seeking redress.
Ultimately, the efforts of the Ministry of Finance and the National Treasury to review the National Tax Policy should also consider how to establish guardrails around these powers to ensure that their application is legitimate.